The Case for Build
AI has lowered the barrier to building. Firms can now create tools that accelerate operations, equip their people, and strip out unnecessary cost and complexity, without waiting on a vendor roadmap or a lengthy IT project.
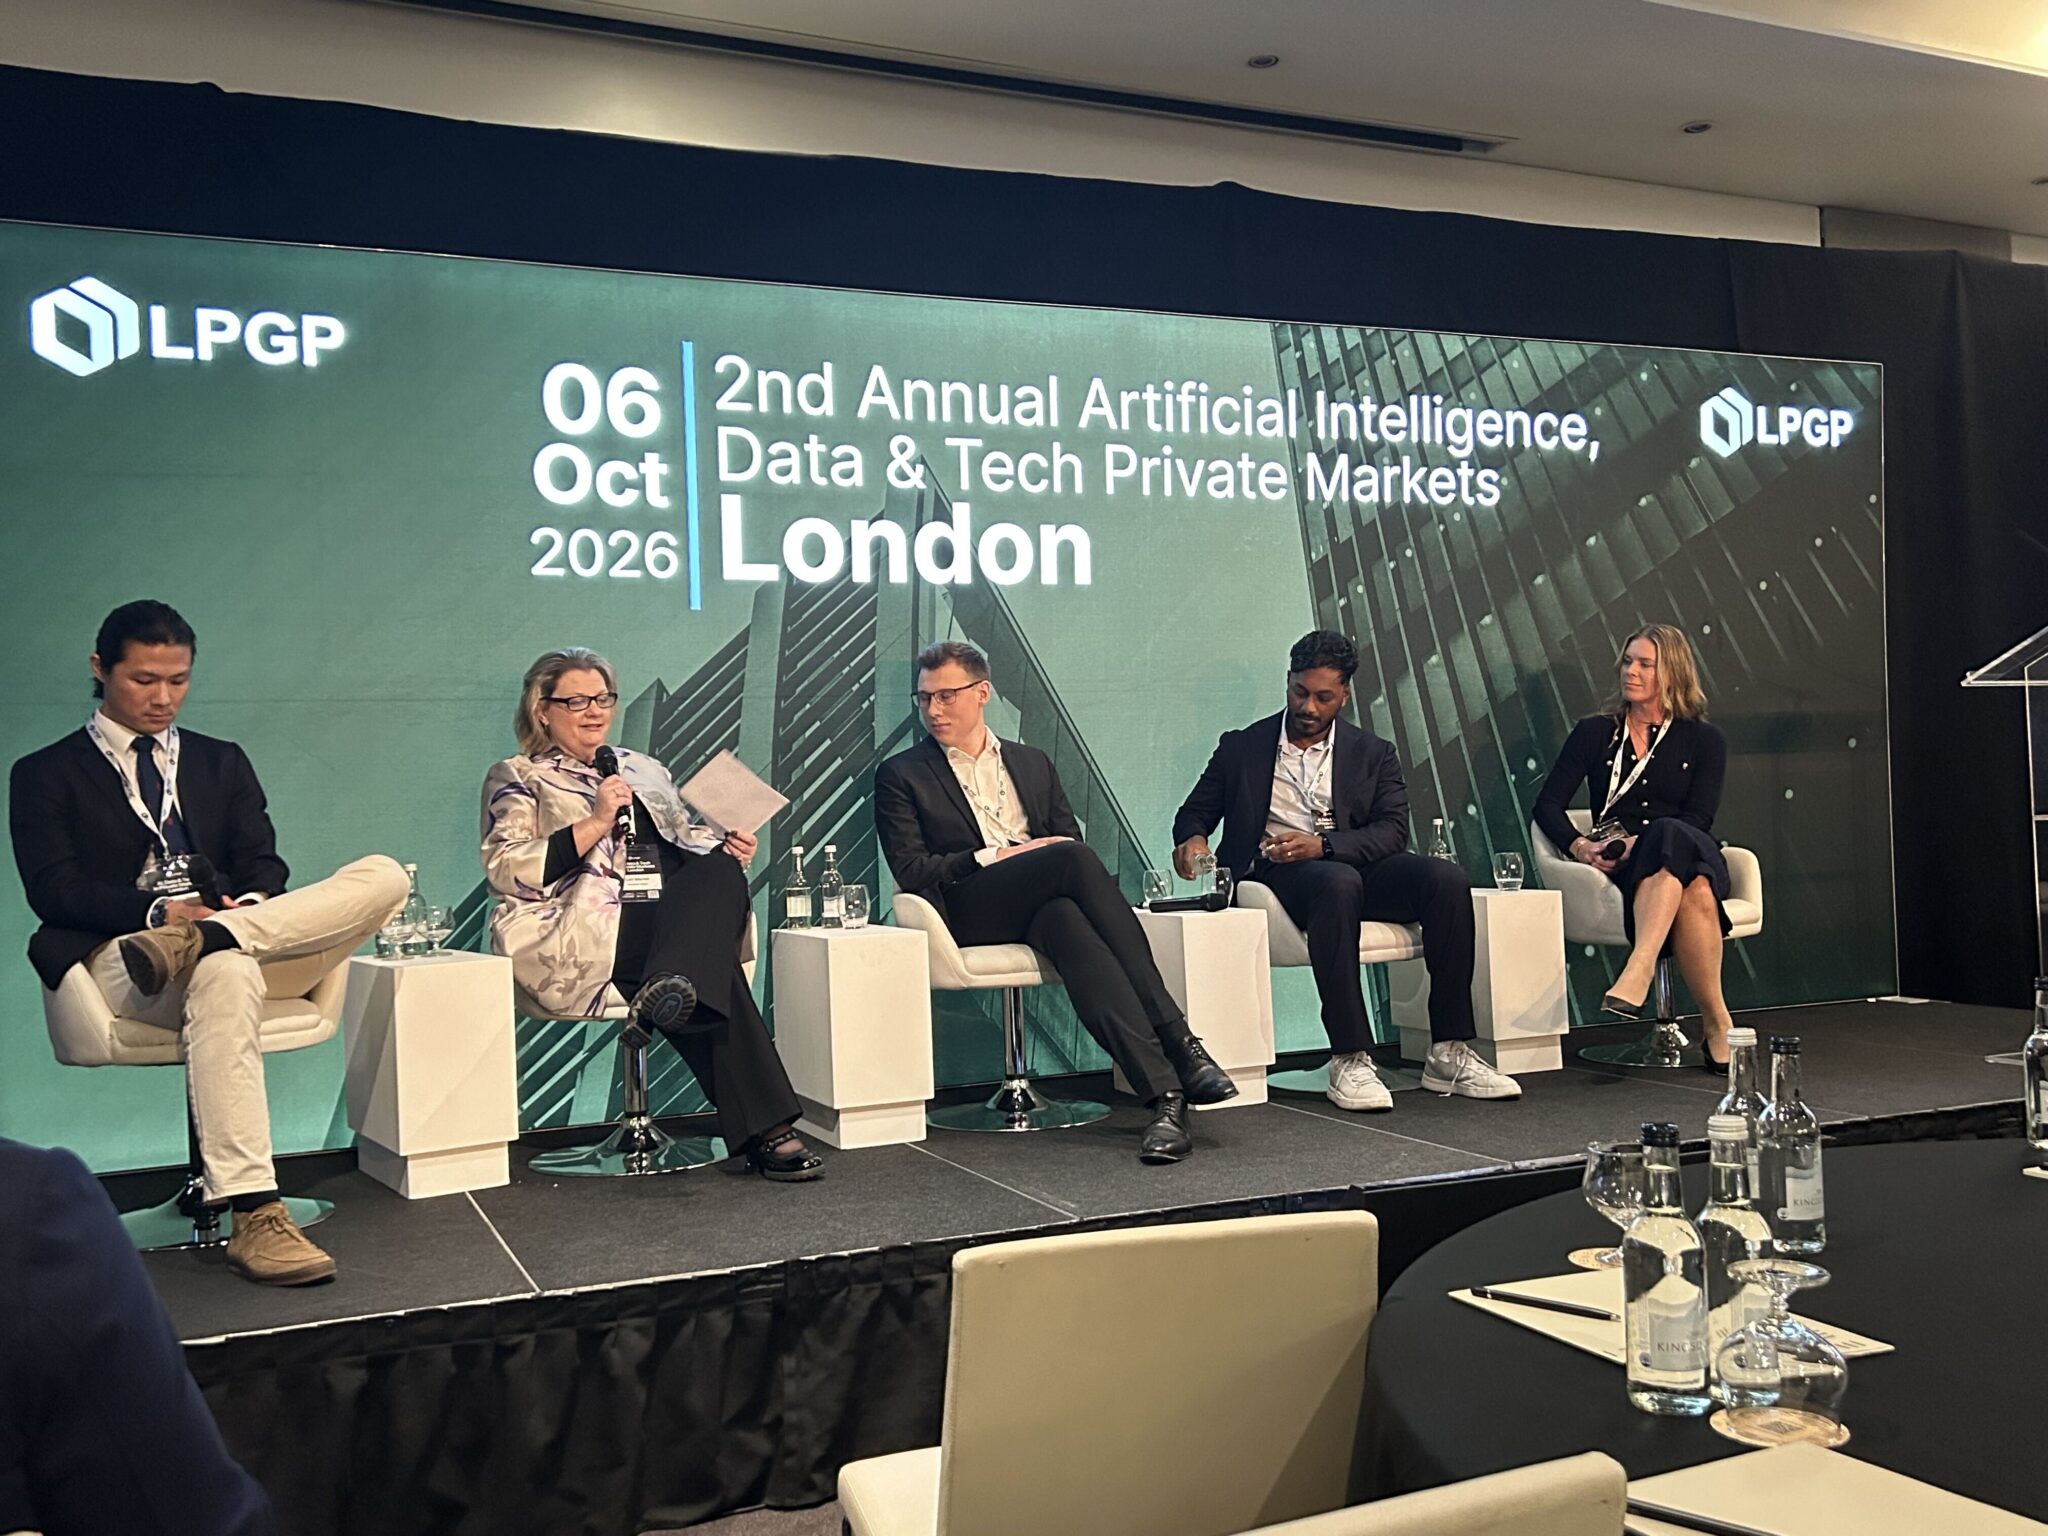
The examples on display were striking. One firm described building and deploying agents that automate multi-step work such as assembling an investment committee memo. Another had built its own ERP system from scratch to underpin its investment operations. The result was a lively lunchtime debate: on one side, the imperative to challenge old ways of working with AI; on the other, the risk of letting the enthusiasm of the moment draw firms into the software business.
InvestorFlow’s take: Both instincts are right, and they are not in conflict. AI is too important not to build with. Firms should be experimenting, putting AI tools in the hands of their people, and building agents that aggregate or visualize existing information in new ways.
Rebuilding core business software for fundraising, distribution, or deployment is a different undertaking. It should be attempted only when the capability is genuinely core to how the firm competes. For a firm like the one above, building its own ERP may well make sense. For most firms, rebuilding established software without deep expertise in developing, deploying, supporting, and continually improving it invites operational failure. Non-core systems are best left to specialists.
What to Build On
Each time the discussion gathered momentum around agents for one function or another, it was brought back to earth by the same two issues: data quality and governance. As in every technology transition, what a firm builds on matters as much as what it builds.
Many attendees favored a measured pace: making sure the underlying data is sound, and keeping humans in the loop so firms don’t institutionalize bad data, flawed analysis, or poor outcomes.
One CIO described a pragmatic dividing line. His firm uses AI on its data for internal-facing work, such as preparing for an investor roadshow or aggregating the large volume of operating metrics across its portfolio. External-facing deliverables, such as an investor report or a term sheet, remain off-limits. For his firm, that is a step too far for now.
Others took a bolder stance. One participant argued that rather than waiting on data quality, firms should overwhelm the problem with as much data as possible. Volume, he suggested, produces better analysis and makes outlier sources easier to spot and assess on their own, an approach he likened to Google’s from its earliest days.
InvestorFlow’s take: Foundations matter, but waiting for data perfection is a mistake that will leave firms playing catch-up. Perfect data is a theoretical state that no firm reaches before starting. The better path is to pick a discrete use case and begin. Doing so reveals the true size of the data problem, surfaces the specific issues to fix, and turns “data quality” from an abstract worry into an actionable work plan. The CIO’s internal/external line is a sensible way to manage risk while that work happens.
How to Build
AI is not only making operations and IT teams more capable. It is putting building power directly into the hands of business users: deal team analysts, investor services associates, value creation teams. That is a significant shift, and it carries a familiar risk. When everyone builds, the result can be fragmentation, with duplicated effort, inconsistent outputs, and tools no one else can trust or reuse.
The challenge therefore moves from enabling building to channeling it: providing a common toolset, building in the controls that produce consistency and trust, and setting priorities so the best efforts become repeatable.
InvestorFlow’s take: We see a clear parallel with the early cloud era, when developers frustrated by the pace of corporate IT went around it to build new applications in the cloud. The organizations that benefited most were not those that clamped down, but those that embraced the energy and gave it structure.
One firm’s CTO described exactly that approach. He spends his days thinking about how to enable a rich fabric of agents and apps built by his own team. The payoff is twofold. First, the business moves faster and innovates closer to the work. Second, he keeps a finger on the pulse of what is being built, which shows him where interest is strong enough to turn an individual experiment into a firm-wide standard. It is a model worth studying.
The Case for Buy
The appetite to build was palpable. There is clear pent-up demand for agents, apps, and infrastructure software to move firms forward, even if the lines between them are a bit blurred in practice. Firms are right to want to build and experiment.
But software providers are in the business of building too, and that is precisely the point. At InvestorFlow, we frequently co-develop agents and apps with clients and partners, which lets us bring the industry’s collective experience, including hard lessons learned, into our applications and core infrastructure. Our adoption of AI across the front office, from fundraising and deal sourcing to deployment and investor servicing, codifies those lessons so every client benefits from them.
Then there is what happens after launch. Every application has a bold beginning: a clear reason to exist, a problem to solve, and new capabilities to solve it. Then come the less glamorous demands of security, scalability, privacy, user adoption, maintenance, and continued innovation. With foundation models changing as quickly as they are, the effort needed to keep an internally built application current can quickly exceed what most firms want to carry. And retaining the people who built the application is often difficult, which can leave firms out in the cold without the talent or knowledge to keep it running.
That is why specialist providers exist: to apply their comparative advantage to codifying best practice, so firms can treat it as a starting point and direct their own resources toward the innovation that creates genuine competitive advantage.
Striking the Right Balance
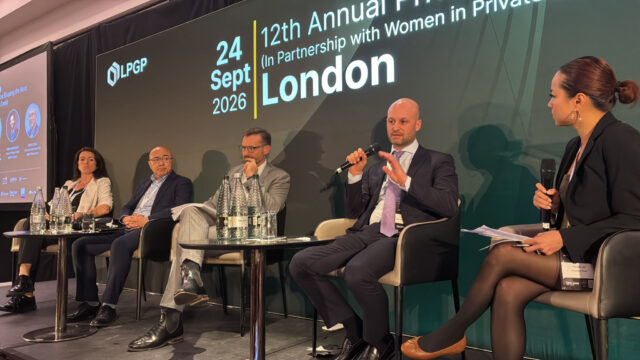
The conference delivered what the best ones do: candid debate among firms, integrators, and providers. The room leaned heavily toward building, and most panelists voted to build their own investment committee memo tools. The audience question that stood out moved the debate from which technology to build or buy to which outcomes a firm needs.
The prudent course today is build and buy. Build the distinct AI agents and tools that drive proprietary advantage. Buy the proven, continually evolving platforms, such as the AI-powered front office InvestorFlow delivers, that give teams a reliable foundation. Firms that strike that balance will move faster, take smarter risks, and put their people in the best position to win.